
 By Adri
Demand is not the same thing as delivery in AI infrastructure. A signed compute contract still needs power, buildings, networking, cooling, servers and eventually a customer acceptance test before it can turn into an operating service.
That physical gap is where Nscale's latest financing lands. Third Point is leading the convertible round, with Nvidia, Apollo-managed funds, Citadel, Hudson Bay Capital, Abu Dhabi Investment Council and 8090 Industries among the new and existing investors.
The headline amount comes in two pieces. Nscale says $2.36 billion is part of the initial tranche at closing. Nvidia has committed another $1 billion, with funding expected in mid-November 2026. So $3.36 billion is the announced financing package, not $3.36 billion that has already landed in Nscale's bank account on September 25.
The bridge to the stock market is literally convertible
These are convertible loan notes rather than a conventional priced equity round. Nscale says the instruments will automatically convert when its initial public offering completes, into ordinary shares for the relevant holders and non-voting shares for Nvidia.
The announcement does not disclose enough of the note economics to calculate a fresh company valuation from the financing alone. There is no publicly stated IPO price in the S-1 either.
Nscale filed its registration statement on September 18 and has applied to trade on the New York Stock Exchange under NSCL. The number of shares to be sold and the proposed price range remain undetermined.
The company's last explicitly announced private valuation was $14.6 billion in March, when it raised a $2 billion Series C. Treating this new convertible package as a new disclosed valuation would therefore add a number Nscale itself has not announced.
$103.4 billion of TCV is a construction obligation as much as a sales achievement
The extraordinary number in Nscale's IPO filing is its contract book. As of August 31, the company reported approximately $103.4 billion of active and contracted total contract value under long-term customer agreements.
TCV is not recognized revenue. It measures contractual value across the committed life of signed agreements. Nscale reported only about $2.6 billion of active TCV on the same date.
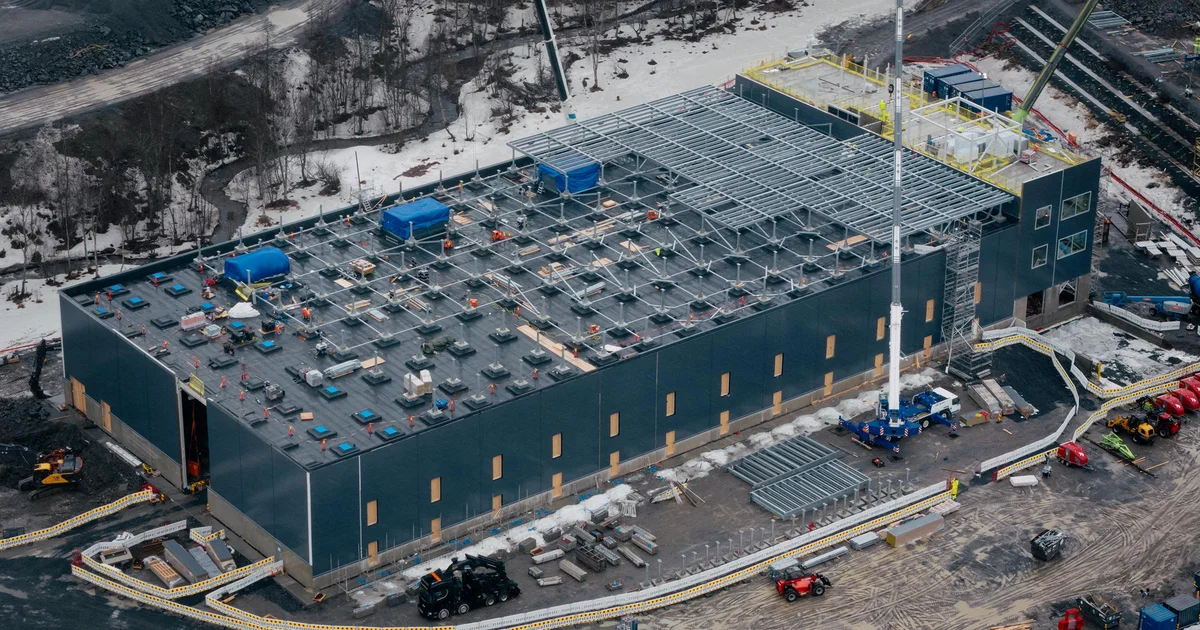
The infrastructure figures make that gap even easier to visualize. The filing lists roughly 25,000 active GPUs and 461,000 active or contracted GPUs. Five data center sites were active; another twelve were contracted. Active and contracted capacity together stood at approximately 1.37 GW.
That does not mean the other 436,000 GPUs are late or missing. It means the economic model is heavily forward-contracted: customers have signed for capacity that Nscale still has to build and successfully deliver.
For an AI neocloud, this is an unusually useful distinction. A software company can often serve another customer by allocating additional virtual capacity. A data center company eventually runs into transformers, cooling loops, construction crews, GPU delivery schedules and megawatts.
Two giant customers dominate the contracted future
Microsoft statements of work signed between September 2025 and April 2026 provide for payments of up to approximately $43.8 billion through 2033, subject to delivery and service-availability requirements.
Anthropic agreements signed in August add up to approximately $44.6 billion for dedicated GPU infrastructure associated with Nscale's Monarch Compute Campus in West Virginia.
Together those maximum contract values amount to roughly $88.4 billion, or about 85% of Nscale's reported $103.4 billion TCV. It is an enormous demand signal and an equally enormous execution concentration.
Nscale's S-1 makes the physical dependency clear. Customer contract terms generally become meaningful as GPU clusters are successfully delivered, and large deployments require significant financing before service revenue arrives.
That is why the new capital matters more than it would at a conventional software startup. Nscale is not financing a larger sales team for contracts it already has. It is financing the equipment and industrial infrastructure needed to make those contracts usable.
Vertical integration makes the buildout heavier, not cheaper to finance
Nscale wants to own more of the AI stack than a simple GPU rental provider. It describes a vertically integrated platform spanning software, compute, liquid-cooled data centers and power infrastructure, including behind-the-meter generation.
The September 25 release says proceeds will be used to accelerate that entire platform, from power plants through data centers to large GPU clusters.
There is a technical logic to the model. Current and next-generation accelerator systems push enormous power densities. Direct liquid cooling, high-capacity networking, storage and dependable power delivery have become part of the compute product rather than background facilities work.
The capital requirement arrives with the integration. Every additional layer Nscale wants to control is another layer that may need to be financed before customers start paying for the completed cluster.
For the first half of 2026, the company reported $140.6 million in revenue and a net loss of approximately $1.02 billion. Those figures do not say what the long-term contracted infrastructure will earn once deployed. They do show how early the operating base remains relative to the promised buildout.
Nvidia is supplier, technology partner and now a billion-dollar note investor
Nvidia's role makes the financing particularly representative of the current AI infrastructure economy.
Nscale builds clusters around Nvidia accelerators and is preparing large deployments of the company's next-generation systems. Nvidia has already invested in Nscale and is now committing another $1 billion through the pre-IPO notes.
The same company can therefore supply the hardware, collaborate on the deployment and finance part of the customer that buys the hardware. Similar feedback loops increasingly connect chip vendors, model developers and cloud infrastructure providers across the AI market.
There is nothing inherently mysterious about that structure: building hundreds of thousands of accelerators' worth of capacity is extremely expensive, while suppliers have a direct interest in ensuring viable customers can finance deployment.
It does mean that the $3.36 billion headline should be read as infrastructure finance rather than just startup fundraising.
Nscale has already signed for vastly more compute than it currently operates. The next stage is turning twelve contracted sites, hundreds of thousands of GPUs and a three-digit-billion-dollar contract book into functioning capacity on schedule.
The new notes provide more capital for that conversion. The IPO may convert the notes into shares; before that happens, Nscale still has to convert a much more stubborn thing: signed demand into powered racks.