
 By Tsuky
Coinbase and Moov announced a partnership on September 10 to bring stablecoin payment infrastructure into the systems used by US community banks and credit unions.
The integration is intended to support consumer stablecoin payments, merchant acceptance and settlement, payouts and real-time funding without requiring each financial institution to build its own crypto custody and transaction stack.
Moov says its growing customer base includes more than 1,000 community banks and credit unions. That figure describes the potential reach of Moov's platform, not 1,000 completed stablecoin deployments. The companies have not disclosed how many institutions are already contracted, piloting the service or live, and they have not announced a universal rollout timetable.
Three infrastructure layers can look like a single banking product
The disclosed architecture gives each participant a fairly distinct job.
The bank or credit union remains the customer-facing institution. Moov supplies the payments platform already connected to the institution. Coinbase sits below that layer with CDP Custodial Wallet accounts for custody and its Payments API for orchestrating stablecoin movement.
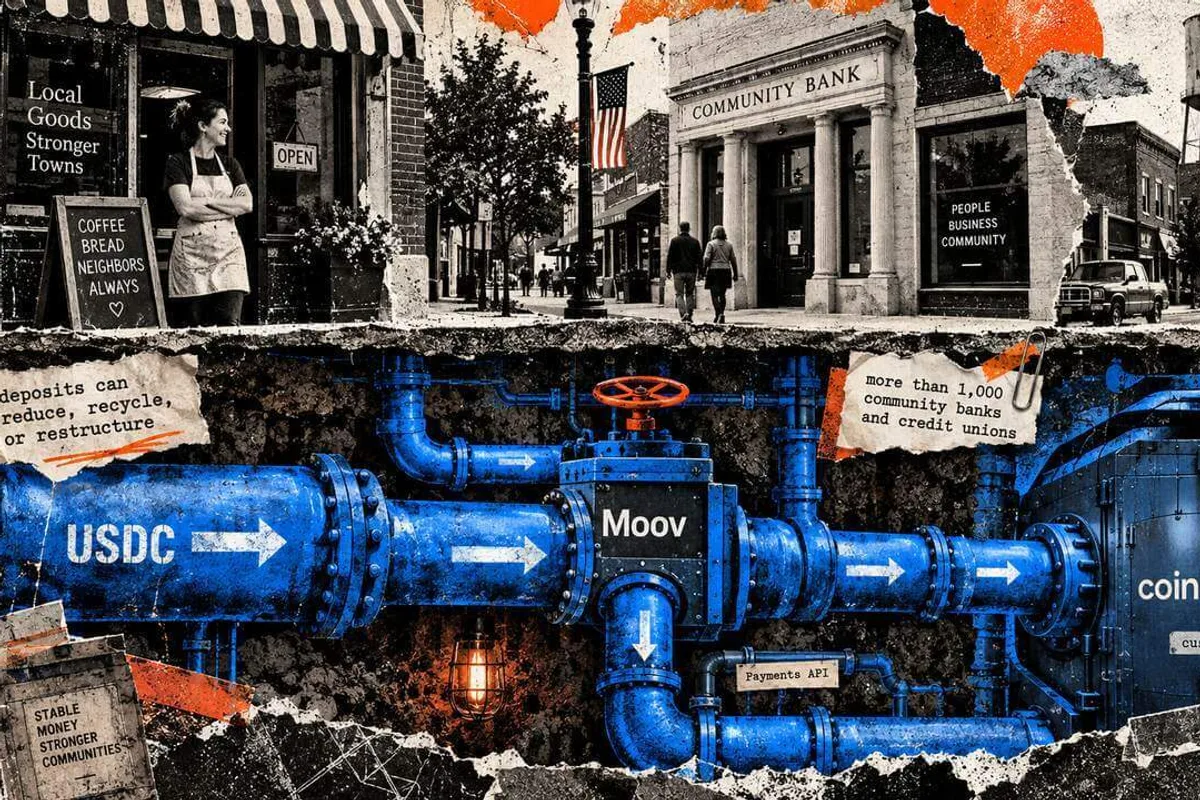
A merchant could therefore interact entirely through a familiar banking relationship while the underlying stablecoin custody and part of the transaction flow are provided by Coinbase.
That removes a substantial engineering burden from smaller institutions. They do not individually need to build blockchain wallet infrastructure, private-key operations, custody systems and the reconciliation stack required to connect those systems to conventional payments.
Stablecoins become one more rail inside Moov
Moov already works across traditional payment infrastructure including cards, ACH and real-time bank payment networks. Coinbase adds another class of rail rather than replacing those systems.
The timing distinction is worth making.
ACH transfers can depend on banking windows and return periods. RTP and FedNow already provide real-time bank payments in the United States. Stablecoins therefore do not introduce the concept of instant digital settlement to community banks.
What they add is an onchain, programmable representation of money that can interact with counterparties already operating through blockchain infrastructure.
Acceptance, settlement and payouts are separate infrastructure problems
Coinbase lists several intended use cases under the partnership.
Consumer acceptance covers someone paying with a stablecoin. Merchant settlement determines how the recipient actually receives value after that transaction. Payouts reverse the direction, allowing a business to send funds to a customer, contractor, supplier or other recipient.
All three look like money movement from the outside. Underneath, they can involve different custody states, funding sources, compliance checks, conversion steps and settlement destinations.
The purpose of the Coinbase and Moov integration is to hide much of that complexity behind existing APIs and banking products.
The bank keeps the customer relationship while Coinbase supplies part of the plumbing
Both companies emphasize that community institutions should not have to send customers elsewhere simply because those customers want to use stablecoins.
A business that wants stablecoin acceptance today may establish a separate relationship with a crypto provider. Embedding the capability in Moov gives the bank a chance to offer that function inside its own payments experience instead.
That does not mean the institution controls every technical layer. Coinbase provides the disclosed custodial accounts and stablecoin movement tools, while Moov connects those functions to the bank's existing payment environment.
The finished product can therefore wear the bank's branding while depending on two substantial external infrastructure providers.
“More than 1,000 banks” is reach, not adoption
This is the most important qualification around the announcement.
Coinbase says Moov has a customer base of more than 1,000 community banks and credit unions. The announcement does not say that all of them have agreed to launch stablecoin products.
The companies have not disclosed the number of pilots, participating institutions, supported stablecoins for individual banks, blockchain networks or institution-by-institution launch dates.
Actual deployments will therefore tell us much more than the size of Moov's addressable network.
The announcement does not say where every dollar ultimately sits
Commercial details are also missing. Pricing, revenue sharing, transaction-data rights, compliance allocation and liability have not been publicly specified.
The balance-sheet question matters as much as the software.
A dollar held as a bank deposit and a dollar represented by a stablecoin can look almost identical inside an app while representing different legal claims and different positions in the financial system.
If bank customers convert deposits into stablecoins, the funding effect depends partly on where the stablecoin issuer holds the corresponding reserves. Money can return to the banking system while moving away from the community institution that originally held the customer's deposit.
The integration can therefore help a bank retain the customer-facing payment relationship without guaranteeing that it retains the exact same deposit economics.
Coinbase increasingly looks like a bank backend provider
The strategy extends beyond Moov.
Coinbase has been expanding partnerships with conventional financial institutions, including PNC, Citi and JPMorgan, while building custody, wallet and payments APIs that can sit inside services carrying somebody else's brand.
That creates a different role for the company. A crypto platform known to consumers is also trying to become infrastructure that the end customer may never see directly.
For a smaller financial institution, that is the appeal of the Moov structure: buy the plumbing instead of building a crypto subsidiary.
Stablecoins are moving closer to the bank account without becoming bank deposits
The more seamless the integration becomes, the easier that distinction may be to overlook.
A customer could eventually use the same banking interface to hold deposits, pay by card, receive a FedNow transfer and make a stablecoin payment. Those experiences can sit centimeters apart on a screen while relying on very different networks and legal protections.
That is arguably the bigger shift behind the Coinbase-Moov partnership. Stablecoins are gradually moving from a separate destination labeled “crypto” toward becoming another money-movement option embedded inside ordinary financial products.
The question is no longer whether a community bank can interact with a blockchain. Coinbase and Moov are designing the system so that the bank may barely need to notice when it does.